How to Create Finance and Business Documentaries with AI
A Practical Faceless Video Format
Investigative business storytelling + verifiable financial data + clear visual explanations + transparent commercial disclosures.
Finance and business documentaries can make complicated subjects understandable: how a company earns revenue, why a business model succeeds or fails, how a market is structured, or what a major economic change means for ordinary customers. The strongest videos combine a clear story with careful research. They do not turn a dramatic chart into proof, confuse a company’s claims with independently verified facts, or suggest that viewers are guaranteed to make money.
This guide explains how to choose a researchable story, read company reports, check financial figures, build scripts and visuals with AI, and create a repeatable production workflow. It is an educational guide for creators, not investment, tax, or legal advice. A disclaimer does not make inaccurate claims safe: every material statement still needs evidence and context.
1. What Makes a Strong Finance or Business Documentary?
A documentary needs more than a company name, a stock chart, and dramatic music. It should answer a specific question and show viewers how the evidence supports the explanation. A useful story might investigate how a retailer makes money, why a once-popular product lost market share, how a subscription business calculates recurring revenue, or why a company’s reported profit differs from its cash flow.
Before researching, write the central question in one sentence. Then define the audience’s starting knowledge. A beginner may need a plain-language explanation of revenue, operating costs, debt, margins, and cash flow before the story reaches more advanced analysis. Avoid using technical vocabulary as decoration; explain each term when it first matters.
Choose a question, not just a trending ticker
- Business-model story: How does the company earn money, who pays it, and what does it cost to deliver the product?
- Rise-and-fall story: Which decisions, market changes, competitive pressures, or operational problems contributed to the outcome?
- Industry explainer: How do suppliers, customers, distributors, regulators, and competitors interact?
- Economic mechanism: How can interest rates, inflation, exchange rates, or a supply shortage affect a specific business?
- Claim investigation: Does a widely repeated claim match the company’s filings, audited accounts, or other reliable evidence?
Do not select a story solely because a headline promises a dramatic result. First check whether enough trustworthy material exists to explain it fairly. If the evidence is thin, choose a narrower question or wait for better documentation.
2. Research Companies with Primary Sources
For a U.S. public company, the SEC’s EDGAR database is a useful starting point because it provides public access to company filings. Investor.gov explains the main reports and how to read them. An annual Form 10-K describes the business, risk factors, management’s discussion, and audited financial statements. A Form 10-Q provides quarterly updates and unaudited financial statements. A Form 8-K reports certain significant events between periodic reports.
Start with the company’s own filing, not a social-media summary. Read the reporting period and filing date carefully: a figure from a previous fiscal year should never be presented as if it were current. For international companies, use the relevant regulator’s official filing system and identify the accounting period and reporting framework.
What to look for in a company filing
- Business description: What does the company actually sell, and which customers or markets does it serve?
- Revenue: Which products, services, regions, or segments contribute to sales? Is the figure quarterly, annual, or trailing twelve months?
- Profitability: Compare gross profit, operating income, and net income. They answer different questions and should not be treated as interchangeable.
- Cash flow: Check cash generated by operations and the company’s investing and financing activities. Accounting profit and cash movement are not identical.
- Debt and liquidity: Review borrowings, interest obligations, cash balances, maturities, and the company’s discussion of liquidity risk.
- Risk factors: Note material legal, operational, competitive, regulatory, supply-chain, and market risks described in the filing.
- Management discussion: Treat management’s explanation as an attributed viewpoint. Compare it with the reported numbers and independent evidence.
Primary documents are essential, but they are not a guarantee that every interpretation is correct. The company prepares its disclosures; the creator still has to explain what they do and do not establish. Pair company reports with relevant regulator releases, court documents, audited reports, industry data, and reputable independent reporting when the story requires them.
Useful starting points: Investor.gov: How to Read a 10-K; Investor.gov: Using EDGAR; and the SEC company filings search.
3. Build a Claim-by-Claim Research File
Before writing narration, create a research table. Each important statement should have a source, date, reporting period, and note explaining exactly what the source supports. This makes it easier to update the video later and prevents a common error: taking a true number from one context and using it to imply something the source never said.
| Claim to verify | Evidence to record | Common mistake |
|---|---|---|
| Annual revenue | Filing, fiscal year, currency, and segment definition | Mixing quarterly and annual figures |
| Profit or loss | Income statement line and accounting period | Calling revenue “profit” |
| Market share | Research provider, market definition, geography, and date | Presenting an estimate as an official company figure |
| Layoffs or closures | Company announcement, regulator filing, or reliable reporting | Repeating an unconfirmed social post |
| Cause of a decline | Multiple sources and clearly attributed analysis | Presenting correlation as proven causation |
| Forecast or valuation | Named analyst/model, assumptions, and forecast date | Presenting a projection as an established fact |
Keep three categories separate throughout the script: reported fact (what a dated source states), analysis (your explanation of what the evidence may mean), and forecast or opinion (a conditional view about what could happen). Use phrases such as “the filing reports,” “management said,” “the data suggests,” and “one possible explanation is” to show viewers which category they are hearing.
If sources disagree, do not silently choose the most dramatic number. Explain the difference in definitions, dates, methodology, or scope. If you cannot resolve the discrepancy, state that limitation or leave the figure out. Never invent a citation, quote, chart value, executive statement, or financial result to fill a gap.
4. Explain Financial Numbers Without Misleading Viewers
Financial storytelling becomes clearer when each metric is defined in everyday language. Revenue is money earned from sales before expenses are deducted. Gross profit is revenue minus the direct costs included in cost of revenue. Operating income reflects profit from operations after operating expenses. Net income is the bottom-line accounting result after other items, including taxes and financing costs, are accounted for. Cash flow statements show cash movements; they are not simply another version of the income statement.
Use comparisons that are genuinely comparable
When comparing two companies, check whether they report the same period, currency, segment scope, and accounting measure. A business with higher revenue is not automatically more profitable. A company with a higher market valuation is not necessarily growing faster or carrying less risk. If you use a ratio, define its numerator and denominator, state the date, and explain what the ratio cannot tell the viewer.
For charts, label the source, units, date range, and whether values are nominal or adjusted for inflation. Do not crop an axis to exaggerate a small movement. If you use a logarithmic scale, identify it. If the chart is an illustration rather than historical data, label it clearly as illustrative. Never create a fake stock-price screen and present it as a real market quote.
A simple example: revenue is not profit
Imagine a fictional company reports $100 million in sales and $70 million in direct costs. Its gross profit is $30 million. If it then spends $20 million on operating expenses, operating income is $10 million before other items. This simplified example does not include every possible accounting adjustment, tax, or financing cost. Its purpose is to show why a headline about “$100 million in revenue” does not mean the company earned $100 million in profit.
5. Step 1: Write an Investigative Follow-the-Money Script
Organize the documentary around a question and a sequence of evidence. A practical structure is: opening question, background, how the business works, the key numbers, the turning point or tension, competing explanations, limitations, and a measured conclusion. Each section should add new information rather than repeat the same claim with different wording.
Use a verified fact or an honest question for the opening. Do not invent a shocking statistic just to create a hook. Introduce the company and time period early, explain the business model before discussing performance, and make transitions show why the next piece of evidence matters. If the story includes allegations, litigation, or disputed conduct, attribute them precisely and include relevant responses or outcomes when available.
Act as a careful business-documentary scriptwriter. Develop a researched outline and then a narration script about [COMPANY, INDUSTRY, OR ECONOMIC EVENT]. The central question is [QUESTION]. Use only the source notes I provide. For every material figure, state the source, reporting period, currency, and date. Separate reported facts, management statements, independent analysis, estimates, and forecasts. Explain technical terms in plain language and add [DATA VISUAL] cues with the exact data needed. Identify gaps or conflicting evidence instead of filling them in. Do not invent quotes, events, figures, sources, or causes. Do not make personalized investment recommendations or promise returns. End with a balanced conclusion that answers the central question and states what remains uncertain.6. Step 2: Generate Visuals That Clarify the Story
Use a consistent visual identity, but let the evidence determine what appears on screen. A cinematic look can make an explanation engaging; it must not imply that a fictional scene is documentary footage. Label illustrative reconstructions, AI-generated scenes, hypothetical diagrams, and simulated interfaces when a viewer could reasonably mistake them for real evidence.
For a data graphic, specify the exact values, source, date range, units, and labels before generating it. It is often safer to build the chart from verified data in a spreadsheet or editing tool than to ask an image generator to invent chart text. AI image tools can misspell labels or create plausible-looking but false numbers. Review every visual manually.
Master Prompt A: 3D Isometric Data and Wealth Dioramas
3D isometric miniature diorama illustrating [THE VERIFIED BUSINESS CONCEPT], a modern financial research environment with abstract data cubes, a restrained emerald-green and warm-gold palette, dark obsidian background, carefully arranged architectural forms, cinematic studio rim lighting, premium editorial documentary aesthetic. No readable text, no company logos, no fabricated numbers, no real-time trading interface, no implication that this is an actual photograph or a real financial result. Leave clean negative space for verified labels to be added in post-production.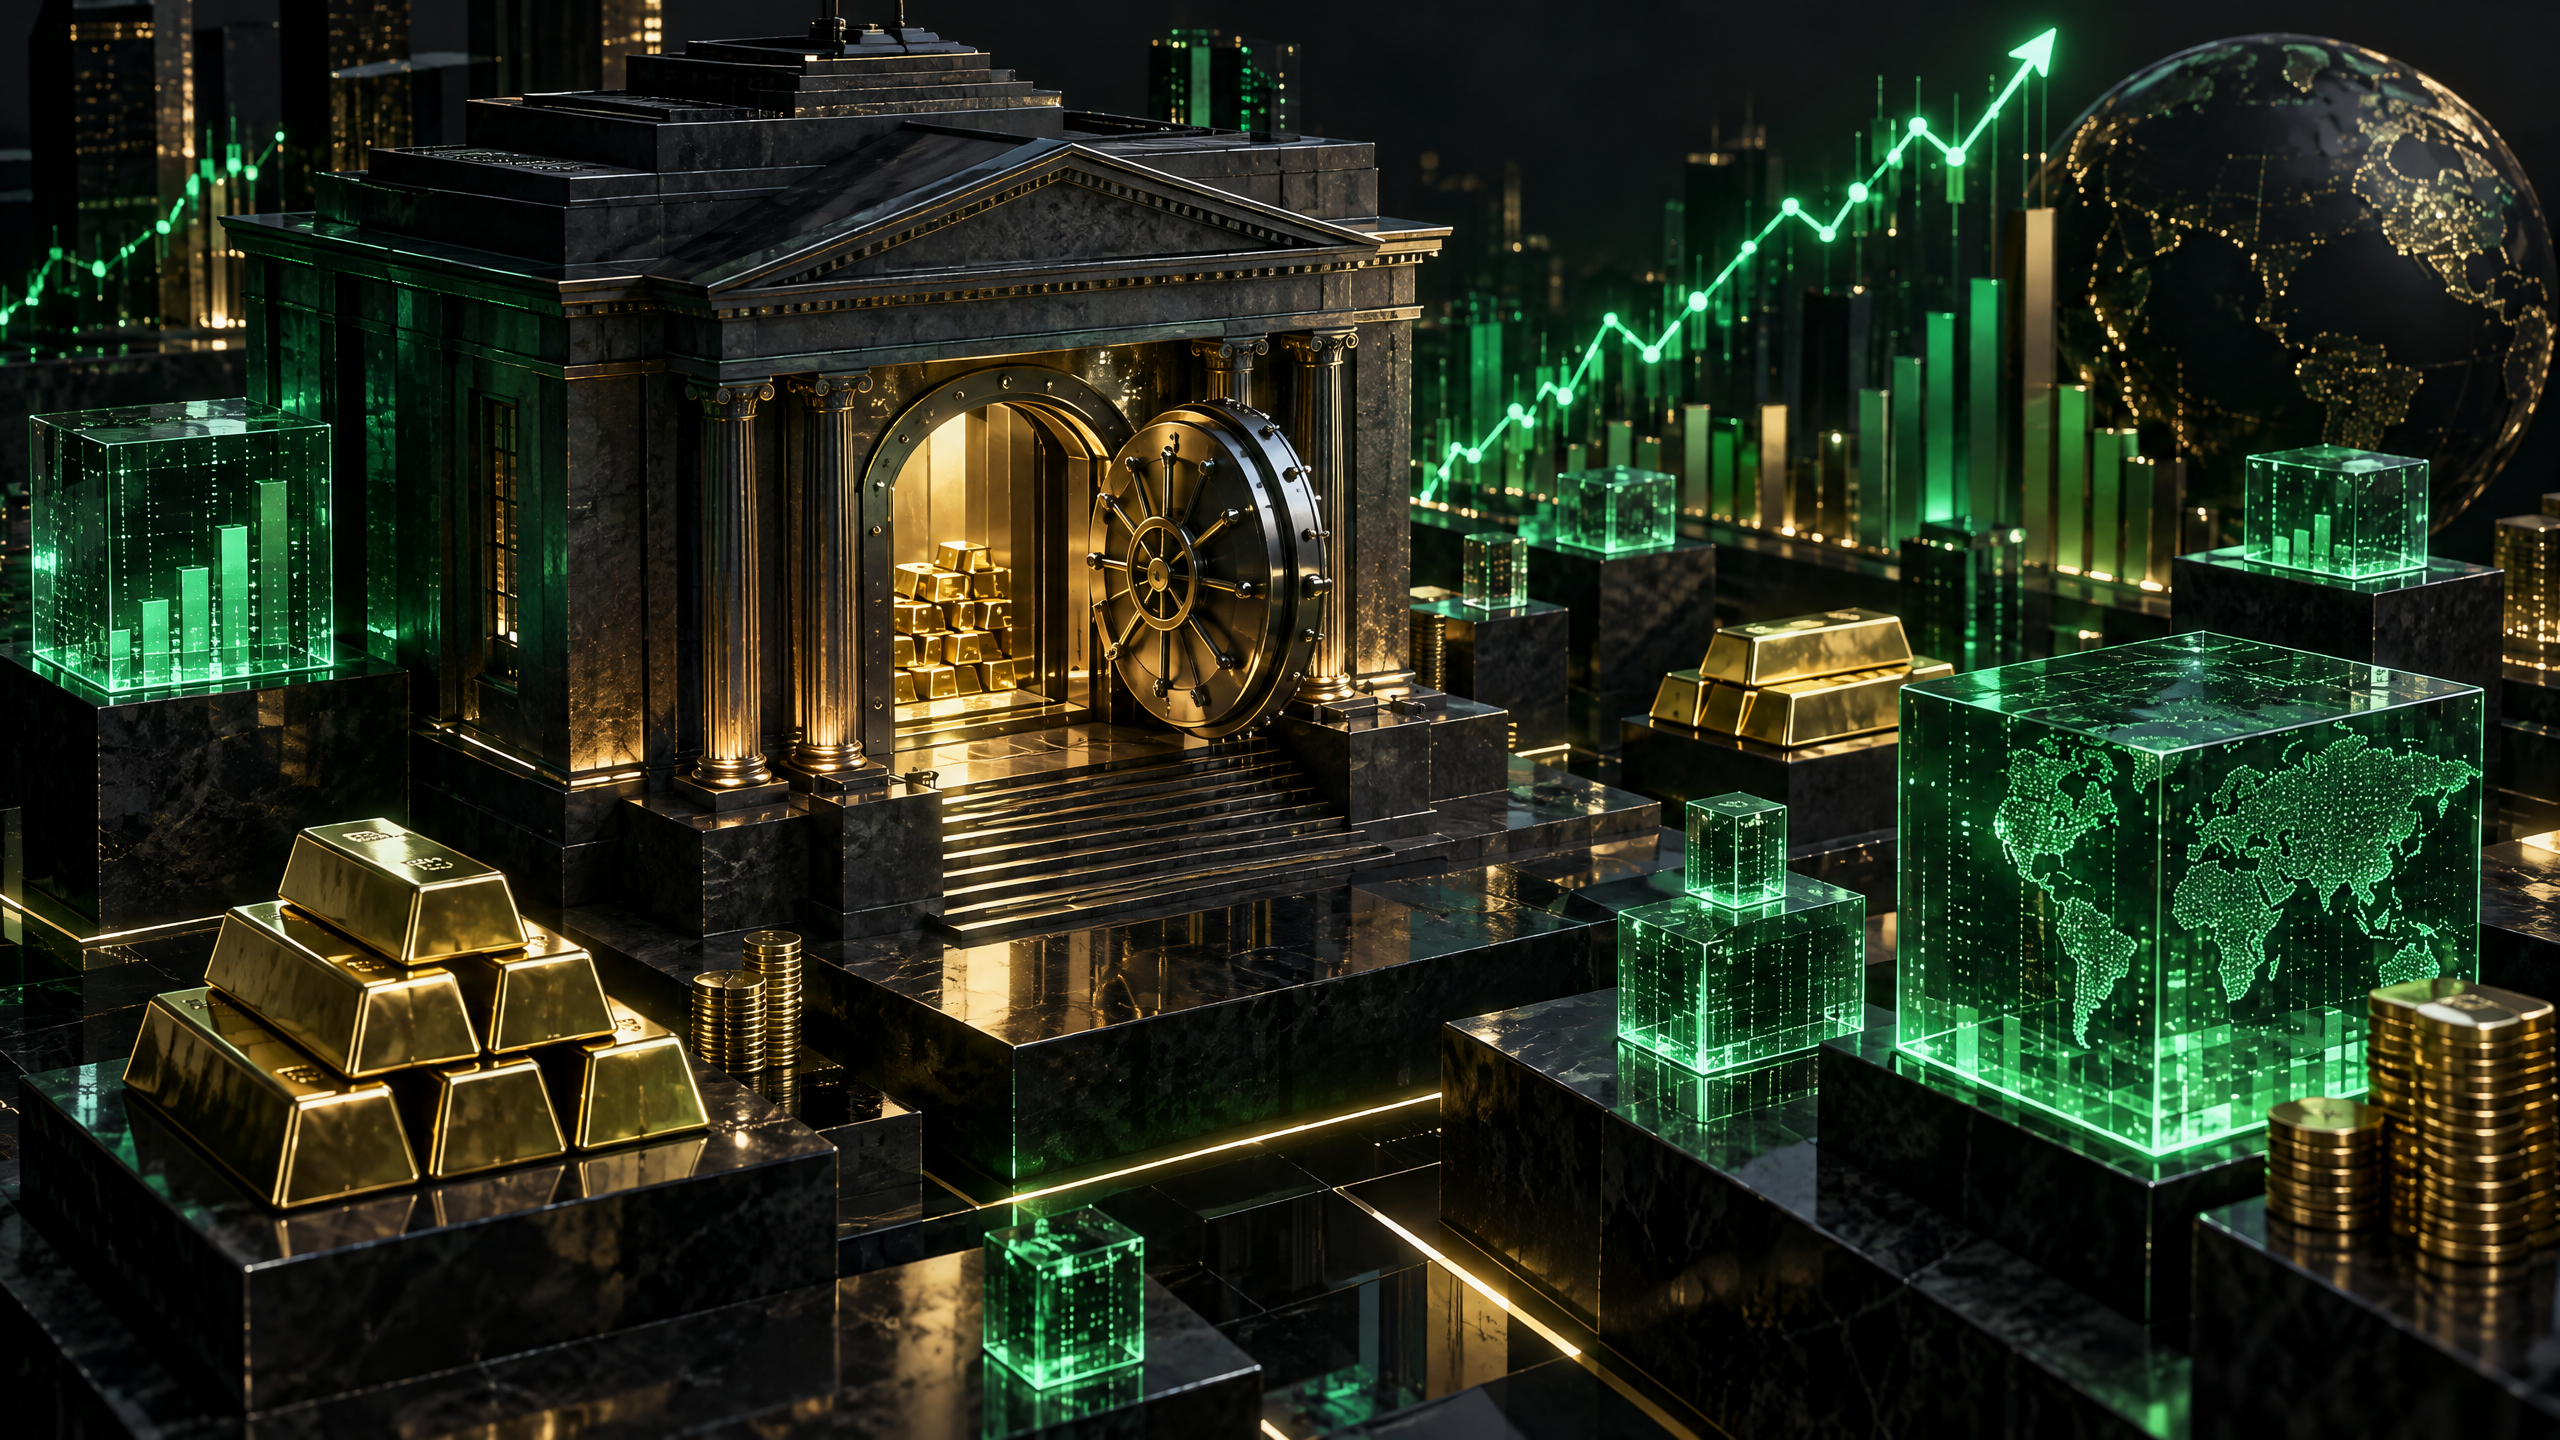
Master Prompt B: Corporate Thriller and Boardroom Noir
Cinematic editorial illustration of a fictional executive silhouette in a high-rise glass boardroom at night, looking over a stylized financial district, restrained navy and crimson lighting, reflections on glass, atmospheric investigative-business documentary mood. Clearly fictional, no identifiable real executive, no real company logo, no readable stock prices, no fabricated headline, no claim that the scene depicts an actual event.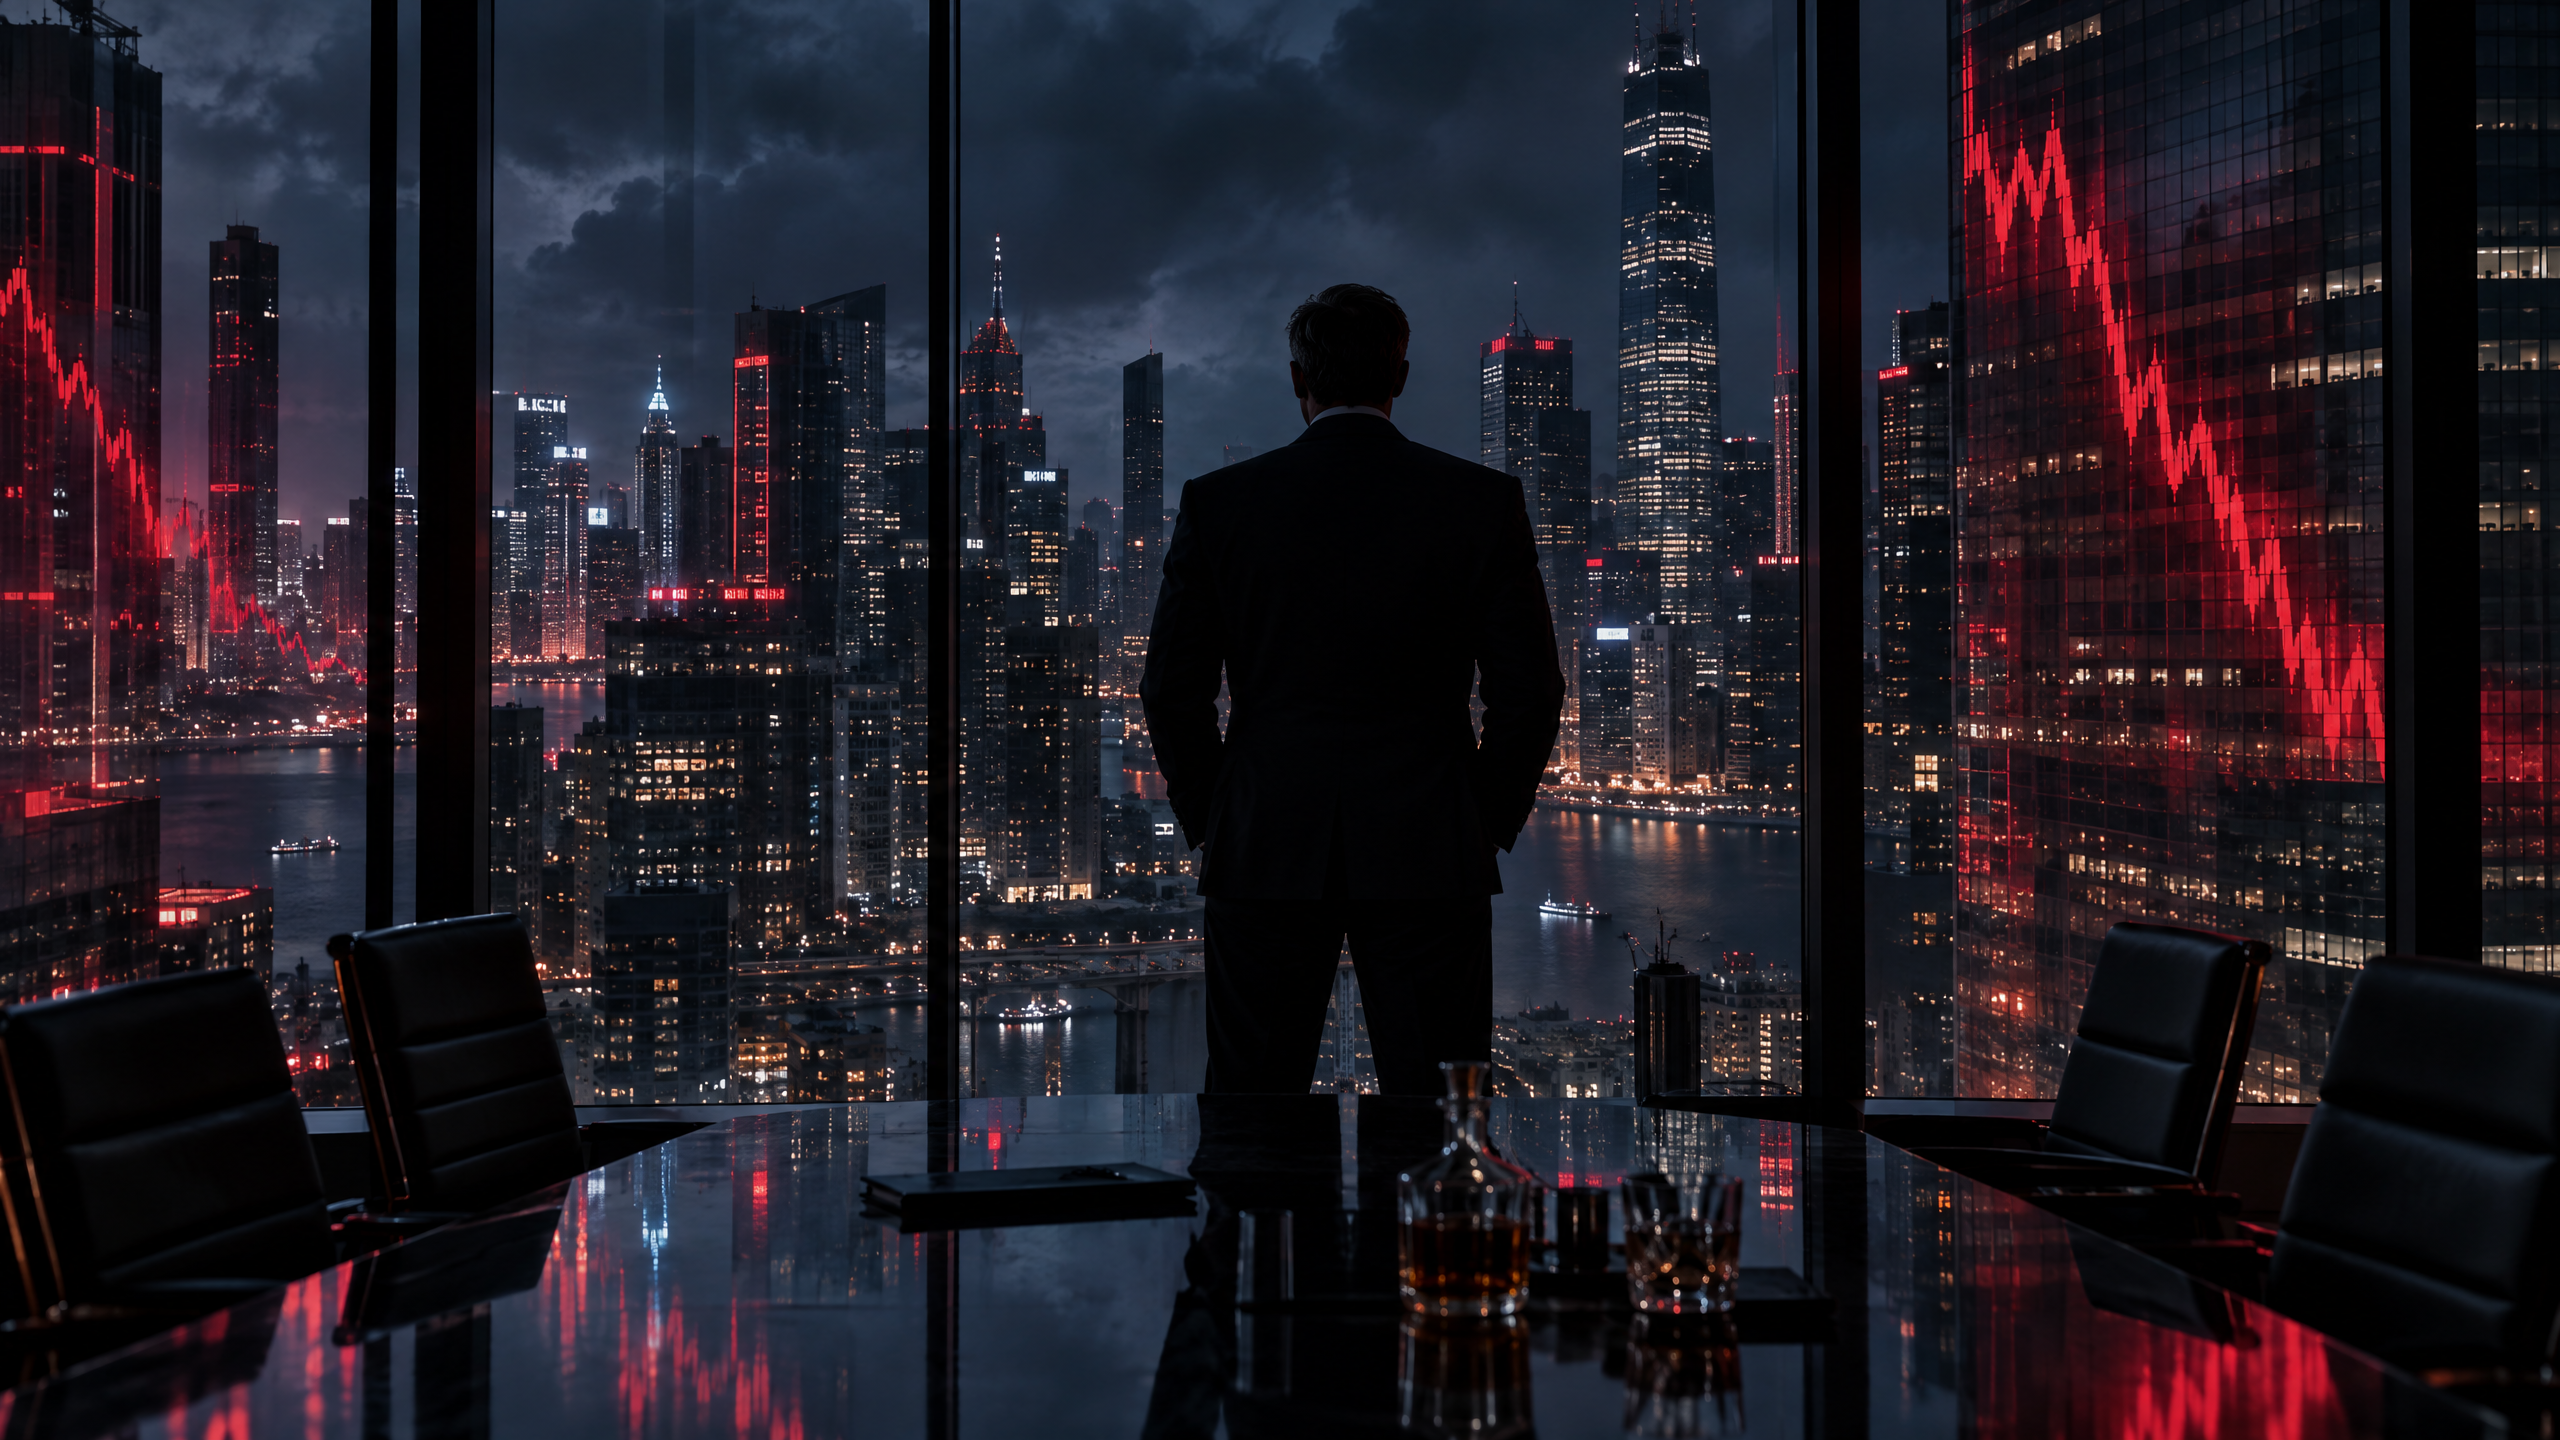
Master Prompt C: Evidence-Led Financial Infographic
Create a clean 16:9 editorial infographic layout for a business documentary about [TOPIC]. Reserve distinct areas for a verified chart, a short definition, a timeline, and a source note. Use a restrained dark background, high-contrast accessible typography, consistent grid spacing, and simple icons. Do not invent, calculate, or render any data. Leave all chart values, company names, dates, and citations as blank placeholders so I can insert the verified information manually.7. Step 3: Add Motion, Narration, and Sound with Restraint
Use slow camera moves, clean transitions, and animated callouts to guide attention to the relevant evidence. A chart should remain on screen long enough to read. When a number changes, show the period and units. Avoid rapid zooms that make a minor fluctuation look like a crisis. Sound design can create atmosphere, but it should not turn an ordinary business update into an implied scandal or emergency.
For narration, define acronyms on first use and read figures naturally. If a number is important, show it on screen and say what it measures. Check pronunciation of company names, currencies, and technical terms. AI voice generation may help with production, but the script, research, analysis, and editing still need meaningful human review.
Act as a documentary fact-checking editor. Review this draft against the supplied source list. Create a table with each factual claim, the exact supporting source, the relevant date or reporting period, whether the source directly supports the wording, and any missing context. Flag unsupported causation, outdated figures, ambiguous units, misleading comparisons, invented quotations, unverified allegations, and chart labels that cannot be traced to data. Do not silently rewrite uncertain claims as facts. Suggest cautious wording or mark the claim [REMOVE / VERIFY].8. Finance Content, AI Use, and YouTube Monetization
Using AI tools does not by itself establish that a video is original or eligible for monetization. YouTube’s channel monetization policy says content should be original and authentic, and it identifies repetitive or mass-produced material as inauthentic content. Reviewers may assess the channel’s main theme, most-viewed and newest videos, the content responsible for the largest share of watch time, metadata, and About section. A channel that publishes near-identical scripts with only company names and stock images swapped may provide little distinct value.
Build each episode around original research, a different question, meaningful interpretation, accurate graphics, and a clear explanation. Reusing an intro, outro, or visual style is not the same as reusing the substance of every episode. If you use third-party footage, charts, music, or quotations, check the rights and the platform’s reused-content rules; permission or a lack of a copyright claim does not automatically satisfy monetization requirements.
Separately, YouTube asks creators to disclose certain realistic altered or synthetic content. Check the current disclosure guidance for the specific use case. A generated illustrative background is not the same as a realistic synthetic scene that could mislead viewers about a real event or person. Do not use AI to fabricate a CEO statement, earnings call, analyst interview, company announcement, or market event.
Read the current YouTube channel monetization policies and YouTube altered or synthetic content disclosure guidance before publishing. Platform rules can change, so revisit the official pages rather than relying on an old summary.
9. Sponsorships, Affiliates, and Financial Promotions
Finance channels may earn revenue through ads, sponsorships, affiliate links, paid newsletters, research products, or software partnerships. These income sources create responsibilities. Make commercial relationships clear where viewers encounter the recommendation, and do not let a sponsor control the factual conclusion of an investigative video. If a sponsor has a connection to the company being discussed, disclose it and consider whether the conflict makes the story inappropriate to publish.
For U.S.-facing endorsements, the Federal Trade Commission explains that material connections—such as payment, free products, or affiliate commissions—may need clear and conspicuous disclosure. A platform’s built-in paid-promotion tool may be useful, but do not assume it replaces a plain-language disclosure that viewers can notice and understand. The exact legal obligations depend on the audience, location, and circumstances; creators outside the United States should also check the rules that apply in their own jurisdiction.
Examples of straightforward wording include “This video is sponsored by [Brand]” or “We may earn a commission if you buy through these links.” Place the disclosure near the endorsement or link, not hidden after a long list of unrelated text. Never describe a paid placement as independent research, and never claim to have tested a product if you have not.
Official guidance: FTC Disclosures 101 for Social Media Influencers and FTC Endorsement Guides: What People Are Asking.
10. Revenue Expectations: RPM Is Not a Niche Promise
Finance is often discussed as a high-value advertising category, but that does not mean every finance channel earns more than every entertainment channel. YouTube does not publish a guaranteed RPM for a niche, and a creator cannot infer future income from a topic label alone. Actual revenue can vary with audience geography, advertiser demand, seasonality, video format, monetized playbacks, ad suitability, viewer behavior, and other revenue sources.
RPM is a creator-facing metric that estimates revenue per thousand views under YouTube’s analytics definition; it is not the same as an advertiser’s CPM. It can also include more than advertising revenue, depending on the analytics view. Compare like with like: use the same channel, time period, content format, and metric definition. Do not compare one creator’s reported RPM with another creator’s CPM and present the difference as a reliable benchmark.
For Shorts, YouTube describes a revenue-sharing system in which eligible creators receive 45% of the revenue allocated to them from the Shorts Creator Pool. That percentage is a platform allocation rule, not a promise that creators receive 45% of every ad shown between Shorts or a fixed amount per view. For long-form videos, eligible videos longer than eight minutes can have mid-roll ads enabled, but ad placement and serving are not guaranteed. Review the official YouTube revenue analytics guide, Shorts monetization policy, and mid-roll ad guidance for current definitions and eligibility.
11. A Repeatable Production Workflow
- Choose a focused question. Define the company, industry, event, time period, and intended viewer.
- Collect primary documents. Save filings, official announcements, regulator materials, and reliable independent sources.
- Build the claim ledger. Record source links, publication dates, periods, currencies, definitions, and unresolved questions.
- Write the outline. Make each section answer one part of the central question.
- Draft and fact-check. Use AI for structure or editing support, then verify every material claim against the original source.
- Prepare visuals. Use real data for charts and label generated scenes as illustrative when appropriate.
- Record and edit. Check narration, pronunciation, captions, pacing, rights, and disclosure requirements.
- Review before publishing. Confirm that title, thumbnail, description, and video make the same evidence-based promise.
- Learn from analytics. Compare retention, returning viewers, traffic sources, and revenue metrics over a meaningful period without treating one upload as proof of a trend.
Keep a dated source folder for every episode. Store the final script, source ledger, chart data, licenses, sponsor disclosures, and correction notes together. If a company later restates results or a material fact changes, you can identify which video sections need an update.
12. A Sustainable Publishing and Improvement Plan
Choose a publishing pace that leaves enough time for research and review. One carefully sourced documentary can be more useful than several rushed videos built from the same template. Repurpose a long video into short clips only when each clip remains accurate and understandable on its own. Include enough context that a short excerpt does not turn a qualified statement into a misleading claim.
Test one creative change at a time, such as the opening question, thumbnail composition, or section order. Review audience retention and returning-viewer patterns alongside qualitative feedback. A high click-through rate is not a success if the title overpromises and viewers quickly leave because the video does not answer the question.
13. Estimate Video Revenue and Script Timing Carefully
Use the YouTube Revenue Calculator to explore how different assumptions affect an illustrative estimate. Treat the output as a scenario, not a forecast or a promise of income. Your actual results depend on your channel’s eligibility, audience, content, monetized views, and revenue mix.
Use the Script Timing Counter to estimate narration length. Read the finished script aloud because pauses, pronunciation, graphics, and scene transitions affect the final runtime. For a stronger opening, you can also use the site’s 3-Second Hook Generator as a brainstorming aid, then check that the hook is supported by the documentary itself.
For related guidance, see Can You Monetize AI Voice Videos on YouTube? and browse the latest FacelessKitAI guides.
Frequently Asked Questions
Do finance documentaries need to give investment advice?
No. A documentary can explain a business model, financial statement, industry, or economic event without recommending that viewers buy or sell a security. Keep educational analysis separate from personalized advice, avoid guarantees, and be clear about uncertainty and conflicts of interest.
Can I use AI to write a business documentary?
AI can help organize research notes, draft an outline, simplify technical language, or suggest visual ideas. It can also produce false facts and citations. Verify claims against original documents, do not use generated quotations, and make sure the finished video contains meaningful original research and explanation.
Where can I find reliable information about a public company?
For U.S. public companies, start with SEC EDGAR filings such as Form 10-K, Form 10-Q, and relevant Form 8-K reports. Add official regulator releases, company announcements, audited reports, and reputable independent reporting when needed. For companies listed elsewhere, consult the relevant market regulator and official disclosure system.
Does a finance channel automatically earn a high RPM?
No. Revenue varies by audience, geography, advertiser demand, content format, monetized playbacks, seasonality, and channel-specific factors. Treat online RPM examples as individual experiences, not guaranteed rates or reliable forecasts.
Can AI-generated visuals be used in a documentary?
They can be useful as illustrations, diagrams, or clearly labeled reconstructions. Do not present generated scenes as real evidence, fabricate a real person’s words or actions, or create fake financial charts. Check YouTube’s current synthetic-content disclosure guidance for realistic altered or generated material.
How do I disclose an affiliate link or sponsor?
Use simple, clear wording close to the endorsement or link, such as “This video is sponsored by [Brand]” or “We may earn a commission from qualifying purchases.” Check the laws that apply to your audience and location, and do not rely on vague labels or hidden disclosures.
How often should I publish?
There is no universal schedule that guarantees growth. Choose a pace that allows enough time for source checks, original analysis, editing, and corrections. Consistency is useful only when quality and accuracy remain intact.
Sources and Update Note
Platform guidance and source links reviewed November 10, 2026. Financial filing guidance below is specific to U.S. public-company reporting; other jurisdictions use different regulators and disclosure forms. YouTube and advertising rules can change, so verify current official guidance before publishing.
- Investor.gov — How to Read a 10-K
- Investor.gov — Using EDGAR to Research Investments
- U.S. Securities and Exchange Commission — Search Filings
- YouTube — Channel Monetization Policies
- YouTube — Altered or Synthetic Content Disclosure
- YouTube — Understand Ad Revenue Analytics
- YouTube — Shorts Monetization Policies
- YouTube — Mid-roll Ads
- Federal Trade Commission — Disclosures 101 for Social Media Influencers
- Federal Trade Commission — Endorsement Guides FAQ